
The dark web has long attracted attention from cybersecurity professionals, researchers, journalists, and the general public stash patrick . Its association with anonymity, hidden services, privacy technologies, and cybercrime has created a complex reputation. Among the names that may appear in discussions of underground marketplaces is Stash Patrick, a term connected in some online discussions with illicit payment-card markets and compromised financial information.
For beginners, understanding Stash Patrick is less about learning how to access an underground marketplace and more stashpatrick.cc about understanding what such markets represent. Studying the risks associated with these environments can help consumers recognize financial threats, businesses strengthen their security programs, and researchers better understand the evolution of cybercrime.
This article examines the dark web marketplace experience from a cybersecurity and awareness perspective without providing instructions for accessing or participating in illicit services.
What Is the Dark Web?
The internet is commonly divided into several broad layers.
The surface web includes websites that are publicly accessible and generally indexed by search engines. Examples include news websites, public company pages, blogs, and online stores.
The deep web consists of online resources that search engines do not normally index. Private email accounts, online banking portals, corporate databases, and subscription platforms are examples.
The dark web is a smaller part of the internet that uses technologies designed to provide additional anonymity. While these technologies can support legitimate privacy and communication needs, some hidden services have also been used for criminal purposes.
It is important not to assume that everything on the dark web is illegal. However, certain underground marketplaces have become associated with activities such as stolen-data trading, financial fraud, and cybercrime.
Understanding Stash Patrick
Stash Patrick may appear in discussions about underground marketplaces involving compromised payment information. The name should not be treated as equivalent to a legitimate credit card provider, bank, or regulated financial platform.
Instead, it can be examined as an example of the broader underground economy surrounding stolen financial data.
Criminal ecosystems can involve multiple participants. Some may specialize in obtaining information through phishing, malware, social engineering, or data breaches. Others may attempt to distribute or monetize the compromised information.
This specialization allows cybercrime to operate as a broader ecosystem rather than as isolated incidents.
Understanding this structure is valuable because a stolen card number or credential may be only one stage in a much larger chain of criminal activity.
What Makes Underground Marketplaces Different?
At first glance, an underground marketplace may resemble an ordinary online marketplace. It may contain listings, accounts, ratings, communication features, and payment mechanisms.
The appearance of professionalism can be misleading.
Unlike legitimate marketplaces, illicit platforms do not provide the same consumer protections, regulatory oversight, or accountability. Participants may be exposed to scams, malicious software, fraudulent listings, or disappearing operators.
A marketplace can also become unavailable without warning because of technical problems, internal disputes, criminal investigations, or law-enforcement activity.
Consequently, an apparent marketplace “experience” should not be interpreted as evidence of reliability or safety.
How Stolen Financial Information Enters Criminal Ecosystems
Payment information can become compromised through numerous methods.
Phishing remains a major source of stolen credentials. Attackers may create messages that imitate trusted financial institutions, retailers, technology companies, or delivery services.
Data breaches can expose large quantities of customer information when attackers compromise business systems.
Malware can target computers and mobile devices, potentially capturing credentials or other sensitive information.
Social engineering is another important threat. Instead of exploiting a technical vulnerability, criminals may manipulate individuals into revealing authentication codes, passwords, or payment information.
Once information is compromised, criminals may attempt to use or distribute it through different channels.
Risks for Consumers
The consequences of payment-data theft can extend beyond unauthorized purchases.
Attackers may combine payment information with names, addresses, email accounts, passwords, or other personal information. This can increase the risk of identity-related fraud and account takeover.
Password reuse can make matters worse. If a victim uses the same password across multiple services, a compromise at one website may provide attackers with an opportunity to target other accounts.
Consumers should therefore use unique passwords and enable multi-factor authentication for important services.
Regularly reviewing financial statements and enabling transaction notifications can also help identify suspicious activity quickly.
Phishing and Social Engineering
One of the most important lessons from underground financial markets is that criminals do not always need sophisticated technical attacks.
A convincing phishing message can persuade a victim to voluntarily provide information.
Messages may claim that an account has been locked, a payment has failed, or urgent verification is required. The goal is often to create pressure so that the recipient acts without carefully examining the request.
Consumers should avoid clicking unexpected financial links and should instead access services through official applications or verified websites.
Unexpected requests for passwords, payment details, or authentication codes should always be treated cautiously.
The Role of Businesses
Businesses have a major responsibility to protect customer payment information.
Organizations should minimize the amount of sensitive data they store and restrict access to authorized personnel.
Encryption can protect information during storage and transmission, while tokenization can reduce the exposure of actual payment credentials during certain transactions.
Security teams should also monitor systems for unusual activity and maintain effective vulnerability-management programs.
Employee training is equally important. Workers should understand phishing, social engineering, suspicious attachments, and unusual authentication requests.
Modern Payment Security
Financial institutions have developed increasingly sophisticated systems to detect fraudulent activity.
Transaction-monitoring systems can evaluate factors such as spending patterns, transaction timing, location, merchant information, and account behavior.
If activity appears unusual, the financial institution may request additional verification or take protective action.
Tokenization, biometric authentication, multi-factor authentication, device intelligence, and behavioral analysis can provide additional layers of protection.
These technologies do not eliminate fraud entirely, but they can make stolen information more difficult to exploit.
The Research Perspective
Cybersecurity researchers may study underground marketplaces to understand criminal trends. Such research can provide valuable insight into data breaches, credential theft, payment fraud, and criminal infrastructure.
However, responsible research does not require purchasing stolen information or interacting directly with criminal services.
Researchers can rely on security-company reports, academic studies, government publications, court documents, and law-enforcement announcements.
These sources can reveal important information while reducing exposure to malware, scams, illegal transactions, and sensitive personal data.
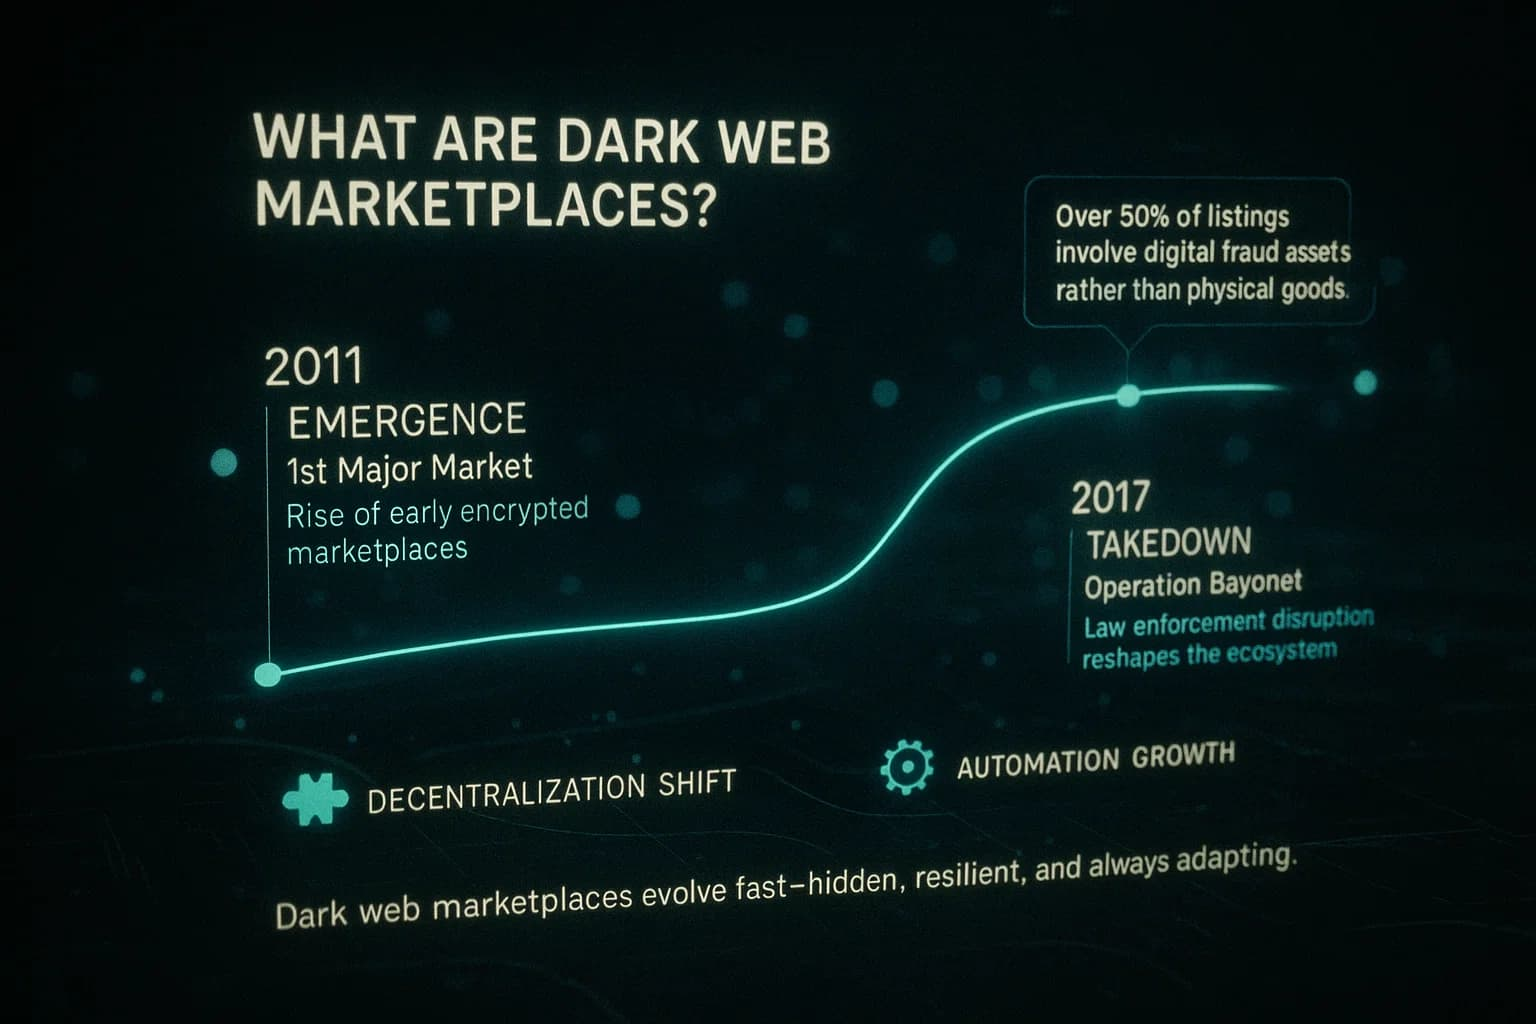
Why Dark Web Markets Continue to Evolve
Underground marketplaces are constantly changing.
Some disappear because of law-enforcement operations. Others collapse because of internal conflicts, technical problems, fraud, or security breaches.
When one platform disappears, participants may attempt to establish alternative communities or services.
This means that cybersecurity professionals should focus on underlying attack methods rather than concentrating solely on individual marketplace names.
Phishing, credential theft, malware, data breaches, and social engineering can remain threats even when a specific marketplace disappears.
How Individuals Can Stay Safe
Consumers can reduce their exposure to threats associated with stolen financial information by following several basic practices.
Use a different strong password for every important account. A reputable password manager can help manage credentials securely.
Enable multi-factor authentication, particularly for email, banking, shopping, and financial accounts.
Keep operating systems, browsers, applications, and security software updated.
Monitor financial accounts regularly and activate transaction notifications where available.
Avoid unexpected links and attachments, especially when messages request sensitive information.
Never purchase, test, or use someone else’s payment credentials.
Looking Toward the Future
The future of digital financial security will likely involve stronger authentication, greater automation, and increasingly advanced fraud detection.
Passkeys and biometric authentication may reduce reliance on traditional passwords. Tokenization can limit exposure of actual payment credentials. Behavioral analytics can help identify unusual activity.
At the same time, criminals will continue adapting their tactics. Social engineering remains particularly challenging because it targets human behavior rather than simply attempting to defeat technical controls.
The strongest defense will therefore combine advanced technology with education and responsible digital behavior.
Conclusion
The dark web marketplace experience associated with names such as Stash Patrick provides a useful case study in the risks surrounding underground financial ecosystems. These environments can involve stolen payment information, compromised credentials, fraud, scams, and other forms of cybercrime.
Understanding these markets does not require participating in them. For consumers, the most important lessons are to protect account credentials, enable multi-factor authentication, monitor financial activity, and recognize phishing attempts.
Businesses can reduce risk through encryption, tokenization, access controls, security monitoring, employee training, and effective incident-response planning.
For researchers, reputable cybersecurity reports and public investigations provide safer ways to study underground markets.
Ultimately, the value of understanding Stash Patrick and similar dark-web references lies in improving cybersecurity awareness. By focusing on prevention rather than participation, individuals and organizations can better protect financial information and prepare for the continually changing landscape of digital crime.
